California Down Payment Assistance 2026 | First-Time Home Buyer Programs
California Down Payment Assistance Programs 2026: Grants & Home Buyer Programs You Should Know About
Think you need $30,000, $50,000 or even $100,000 saved before you can buy a home in California?
You may be surprised.
One of the biggest things I hear from buyers is:
“I can afford the monthly payment, but I don't have enough saved for the down payment and closing costs.”
I also hear:
“I'm self-employed. I don't think I'll qualify.”
“I'm a nurse. Are there special programs for healthcare workers?”
“I've owned a home before. Can I still get down payment assistance?”
The answer is simple: don't count yourself out before you know your options.
I'm Armand Martin, a California Realtor and real estate investor, and I've had success working with first-time homebuyers, nurses and other healthcare professionals, self-employed buyers, veterans, families and repeat buyers using different financing and down payment assistance programs.
I created this guide to make California home buyer programs easy to understand.
Even better, I've included links to the actual programs so you don't have to just take my word for it. Click the links, research the programs yourself, and then let's determine which options may work for you.
IMPORTANT: Down payment assistance programs can change. Funding, interest rates, credit requirements, income limits and eligibility can change or run out. Some programs are grants, while others are second mortgages, deferred loans, forgivable loans or shared-appreciation loans. Your lender should verify current eligibility and terms before you rely on any program.
🏠 How Much Money Do You Really Need to Buy a House in California?
Let's clear up one of the biggest home-buying myths:
You do NOT automatically need 20% down.
Depending on your qualifications and loan program, you may have options such as:
Conventional Loans: Certain programs may allow down payments as low as 3%.
FHA Loans: Qualified buyers may purchase with a 3.5% down payment.
VA Loans: Eligible veterans and service members may qualify for 0% down.
USDA Loans: Eligible buyers purchasing eligible properties may qualify for 0% down.
Then we can look at whether a down payment assistance program can help with some of the money you would otherwise need.
That's where things get interesting.
💰 What Is Down Payment Assistance?
Let's make this really simple.
Imagine you're purchasing a:
$500,000 Home
A 3.5% down payment would equal:
$17,500
And that's before considering closing costs and other expenses.
Now imagine qualifying for a program that provides assistance toward your down payment and/or closing costs.
That's why I tell buyers:
Don't assume you can't buy because you don't have a huge savings account.
Let's find out what you actually qualify for first.
👩⚕️ Nurses & Healthcare Workers: Start Here
If you're a nurse, healthcare worker, teacher, firefighter, EMT or law-enforcement professional, this is one program I would definitely ask your lender about.
GSFA Platinum Program
The Golden State Finance Authority's GSFA Platinum Program provides down payment and/or closing-cost assistance to eligible California homebuyers.
Certain program options provide additional benefits for select occupations, which can include:
🏥 Medical and healthcare workers
🚒 Firefighters and EMTs
👮 Law-enforcement personnel
🍎 Teachers and qualifying education employees
Another major benefit:
You don't necessarily have to be a first-time homebuyer.
Depending on the mortgage and program option, assistance may reach up to 5.5% of the first-mortgage loan amount.
Some assistance may be structured as a second mortgage, while certain portions may be available as gift funds depending on the option and current guidelines.
👉 VIEW THE OFFICIAL GSFA PLATINUM PROGRAM:
https://www.gsfahome.org/programs/dpa/platinum.shtml
Why I Like Looking at This Program
I've worked with buyers in healthcare and other professions who make good money but haven't necessarily had time to save a huge down payment.
You can have a great career and a good income and still need help getting over the upfront-cost hurdle.
There's nothing wrong with looking at every legitimate option available to you.
🔑 Not a First-Time Buyer? Look at GSFA Golden Opportunities
Here's another common misconception:
You don't always have to be a first-time homebuyer to receive down payment assistance.
The GSFA Golden Opportunities Program currently provides eligible California homebuyers with assistance of up to 5% of the first-mortgage loan amount.
Depending on current requirements, the program can work with financing such as:
🏠 FHA
🇺🇸 VA
🌾 USDA
💳 Certain Conventional Loans
For example:
If your first mortgage were $450,000, 5% would equal:
$22,500
That's real money that could make a significant difference in your home purchase.
Remember, assistance isn't automatically free money. Depending on the program structure, some assistance may be provided through a second mortgage or other financing structure.
👉 VIEW GSFA GOLDEN OPPORTUNITIES:
https://www.gsfahome.org/programs/dpa/go.shtml
🌴 First-Time California Buyer? Look at CalHFA MyHome
CalHFA MyHome Assistance Program
CalHFA stands for the California Housing Finance Agency.
Its MyHome Assistance Program is designed to help qualifying first-time homebuyers with their down payment and/or closing costs.
Depending on the qualifying CalHFA mortgage, MyHome may provide assistance based on a percentage of the purchase price or appraised value.
Is CalHFA MyHome Free Money?
No.
This is important.
MyHome is generally structured as a deferred-payment junior loan.
In simple terms:
You are borrowing the assistance.
However, repayment works differently from simply adding another traditional monthly mortgage payment.
That's why you should understand exactly how the loan works before accepting the assistance.
👉 VIEW OFFICIAL CALHFA HOMEBUYER PROGRAMS:
https://www.calhfa.ca.gov/homebuyer/programs/index.htm
🌟 California Dream For All
You've probably seen this program on social media.
CalHFA Dream For All Shared Appreciation Loan
California's Dream For All program was created to help qualifying first-generation and first-time California homebuyers.
The assistance can potentially be significant.
But here's the part I want my buyers to understand:
Dream For All is NOT simply free money.
It's a shared-appreciation loan.
That means you receive assistance toward your purchase, but when certain repayment events occur, you repay the original assistance plus an agreed-upon share of the home's appreciation.
What Does That Mean?
If the home increases in value over the years, the program may share in a portion of that appreciation according to its guidelines.
That's why you should understand both sides:
The benefit today AND the future repayment obligation.
Dream For All also operates through limited application and funding periods, so availability is important.
👉 VIEW CALIFORNIA DREAM FOR ALL:
https://www.calhfa.ca.gov/dream/index.htm
🏡 Chenoa Fund Down Payment Assistance
Another program worth researching is the Chenoa Fund.
Depending on the program option and borrower qualifications, Chenoa Fund can provide down payment assistance with eligible mortgage financing.
Different assistance structures may have different repayment requirements.
👉 VIEW CHENOA FUND:
https://chenoafund.org/
Whenever you're comparing assistance programs, ask your lender these questions:
1. How much assistance am I receiving?
2. Is this a grant or a loan?
3. Do I have a monthly payment on the assistance?
4. Is there interest?
5. What happens if I refinance?
6. What happens when I sell the house?
Those six questions can make comparing programs much easier.
💵 Looking for a $25,000 Home Buyer Program?
NeighborhoodLIFT
NeighborhoodLIFT has offered substantial homebuyer assistance in participating communities.
Depending on location, lender, current funding and program requirements, eligible buyers may have access to significant purchase assistance.
👉 VIEW NEIGHBORHOODLIFT:
https://neighborhoodlift.communityhdc.org/home/
Programs like this can be location-specific and funding-specific.
Just because a program exists does not mean funding is currently available in your city.
Always check current availability.
🚀 Rocket ONE+
Another option buyers may want to research is Rocket ONE+.
This is a conventional financing option designed to reduce the amount eligible buyers need upfront.
👉 VIEW ROCKET ONE+:
https://www.rocketmortgage.com/learn/one-plus
Here's an important tip:
Don't compare loan programs based only on the amount of assistance advertised.
Ask your lender:
“What does my total monthly payment and cash to close look like WITH this program versus WITHOUT it?”
Now you're comparing the whole financial picture.
🌆 Buying a Home in Los Angeles?
California doesn't have just statewide assistance.
There are also local city and county programs.
If you're buying within the City of Los Angeles, you should research the Los Angeles Housing Department's first-time homebuyer programs.
Low Income Purchase Assistance Program — LIPA
LIPA is designed to help qualifying first-time, lower-income homebuyers purchase property within the City of Los Angeles.
Assistance can help with eligible acquisition, down payment and closing expenses according to current program guidelines.
👉 VIEW LOS ANGELES HOMEBUYER ASSISTANCE:
https://housing.lacity.gov/housing/helping-low-income-first-time-homebuyers
The City of Los Angeles also has programs designed for qualifying moderate-income buyers.
👉 VIEW CITY OF LOS ANGELES FIRST-TIME HOMEBUYER PROGRAMS:
https://housing.lacity.gov/housing/first-time-homebuyers
Remember:
City of Los Angeles programs and Los Angeles County programs are not automatically the same thing.
The property's actual location matters.
🌉 Buying in Santa Clara County?
Empower Homebuyers SCC
Buyers purchasing in Santa Clara County should research the Empower Homebuyers program through Housing Trust Silicon Valley.
This program can potentially provide substantial purchase assistance to qualified buyers.
👉 VIEW EMPOWER HOMEBUYERS SCC:
https://housingtrustsv.org/programs/homebuyer-assistance/empower-homebuyers-scc/
🌁 Buying in San Francisco?
San Francisco Downpayment Assistance Loan Program — DALP
San Francisco has its own down payment assistance program for eligible homebuyers.
Because San Francisco home prices are substantially higher than many other California markets, the potential assistance can also be substantial.
But remember:
Large assistance does not automatically mean free money.
Understand the repayment terms before making a decision.
👉 VIEW SAN FRANCISCO DALP:
https://sfmohcd.org/dalp
🌴 Buying in San Diego?
San Diego First-Time Homebuyer Program
The San Diego Housing Commission administers homebuyer programs that can provide qualifying buyers with purchase assistance.
Eligibility and assistance depend on the jurisdiction, household income, property and current program guidelines.
👉 VIEW SAN DIEGO HOMEBUYER PROGRAMS:
https://www.sdhc.org/first-time-homebuyer-program/
🌉 Buying in Alameda County?
AC Boost
If you're purchasing in Alameda County, research AC Boost.
The program is designed to help eligible buyers bridge the gap between what they can afford and the cost of purchasing a home.
👉 VIEW ALAMEDA COUNTY AC BOOST:
https://www.acgov.org/cda/hcd/homeownership/boost.htm
🏠 Contra Costa County Homebuyer Assistance
Contra Costa County buyers may also have access to local homebuyer assistance programs.
Program availability and funding can change.
👉 VIEW HOMEBUYER ASSISTANCE:
https://communityhdc.org/down-payment-assistance-programs/
💼 WISH Homebuyer Program
Workforce Initiative Subsidy for Homeownership
The WISH Program is associated with the Federal Home Loan Bank of San Francisco and works through participating financial institutions.
Funding is generally designed to help qualifying households move toward homeownership.
Availability and amounts can change based on funding cycles.
👉 VIEW WISH HOMEBUYER INFORMATION:
https://www.fhlbsf.com/products/community-programs-grants/wish
🏘️ Buying in San Pablo?
SPLASH
San Pablo's Loan Assistance for Sustainable Housing (SPLASH) program provides another local homebuyer assistance option.
👉 VIEW SPLASH:
https://www.sanpabloedc.org/SPLASH
💰 More California Home Buyer Programs Worth Researching
Depending on your location and qualifications, there may be even more programs available.
Pathway to Homeownership
Potential assistance for qualifying California homebuyers.
👉 https://www.car.org/marketing/clients/downpaymentresource
Delta Housing Affordability Fund
Potential assistance for qualifying buyers within applicable areas.
👉 https://www.deltaaor.com/delta-housing-affordability-fund/
Housing Trust Silicon Valley Home Access
Another homebuyer assistance option for qualifying Silicon Valley buyers.
👉 https://housingtrustsv.org/programs/homebuyer-assistance/home-access-loan-program/
👩⚕️ I'm a Nurse. Which Home Buyer Program Should I Look At?
Start by asking your lender about GSFA Platinum and whether your occupation qualifies under the program's current healthcare-worker provisions.
But don't stop there.
Being a nurse doesn't mean you can only use a “nurse home loan.”
You could potentially qualify for programs based on your:
Income
Credit
Profession
Purchase location
First-time buyer status
Mortgage type
The goal isn't to find a program with the word “Nurse” written on it.
The goal is to find the financing structure that makes the most sense for YOU.
💻 I'm Self-Employed. Can I Still Buy a House in California?
Yes, self-employed buyers can qualify for mortgages.
Owning a business does not automatically prevent you from purchasing a home.
However, documenting your income can be different from someone receiving a regular W-2 paycheck.
Depending on your situation and loan program, a lender may review things such as:
Tax returns
Business income
Profit-and-loss statements
Bank statements
Length of self-employment
Business expenses
I've worked with self-employed buyers, and one of the biggest mistakes I see is someone assuming:
“I write things off on my taxes, so there's no way I can buy.”
Don't guess.
Have a knowledgeable lender actually run your numbers.
You may be closer than you think.
🏠 I've Owned a House Before. Can I Still Get Down Payment Assistance?
Possibly!
Some programs require you to be a first-time homebuyer.
Others don't.
GSFA, for example, has programs that do not require first-time homebuyer status.
And here's something else many buyers don't know:
Depending on the program, being considered a “first-time homebuyer” doesn't necessarily mean you've never owned a home in your entire life.
Some programs use a specific lookback period or other definition.
That's why I don't want you disqualifying yourself.
Let your lender check the actual guidelines.
🤔 Grant vs. Forgivable Loan vs. Second Mortgage
This might be the most important section of this entire article.
Not all “down payment assistance” is the same.
🎁 Grant
Generally, money that doesn't need to be repaid as long as you satisfy the program's requirements.
🕐 Deferred Loan
You borrow the money, but repayment is postponed according to the program terms.
❤️ Forgivable Loan
A loan where some or all of the balance may be forgiven after you meet specific requirements.
For example, you may have to live in the property for a certain number of years.
🏦 Second Mortgage
Another loan secured by the property in addition to your primary mortgage.
Depending on the program, it may have monthly payments or deferred repayment.
📈 Shared-Appreciation Loan
You receive assistance today, but when a repayment event occurs, you may repay the original assistance plus an agreed-upon share of the property's appreciation.
California Dream For All is an example of this structure.
This is why two programs advertising the same amount of assistance can be VERY different financially.
🔥 Can I Combine Down Payment Assistance With Seller Credits?
Sometimes.
This is where having your Realtor and lender working together becomes extremely important.
Imagine we find a house where the seller is willing to contribute toward your allowable closing costs.
Your lender also identifies a down payment assistance program you qualify for.
Now we're looking at your transaction from several different angles:
Down payment
Closing costs
Seller credits
Down payment assistance
Interest rate
Monthly mortgage payment
Cash remaining in savings
My goal isn't simply:
“Can we get you into the house?”
I also want us asking:
“What does your financial situation look like the day AFTER you get the keys?”
Keeping some of your money in savings for emergencies, repairs, moving expenses and life can matter too.
🚨 Don't Just Chase “Free Money”
This is important.
If somebody advertises:
“GET $25,000 FREE TO BUY A HOUSE!”
Ask questions.
Have your lender show you:
OPTION A
Regular mortgage without assistance.
OPTION B
Mortgage with down payment assistance.
Then compare:
Cash needed to close
Interest rate
Monthly principal and interest
Mortgage insurance
Second mortgage payment, if applicable
Total monthly housing payment
Repayment requirements
Refinance restrictions
What happens when you sell
Sometimes assistance can be extremely valuable.
Sometimes using your own money may make more financial sense.
We want to see the whole picture.
🌵 Buying in Palmdale, Lancaster or the Antelope Valley?
This is especially important for my local buyers.
I work with buyers throughout Palmdale, Lancaster and the Antelope Valley, and our purchase prices can create different opportunities compared with higher-priced areas of Southern California.
Depending on your qualifications and the property's location, we can look at options such as:
FHA Loans
VA Loans
USDA Loans
Conventional Loans
GSFA Assistance
CalHFA Programs
First-Time Buyer Programs
Occupation-Based Assistance
and other lender or community programs.
You don't have to understand every program yourself.
That's what your real estate and lending team is for.
🧮 Let's Make Buying a Home Simple
Instead of asking:
“Can I afford to buy a house?”
Let's answer five smaller questions.
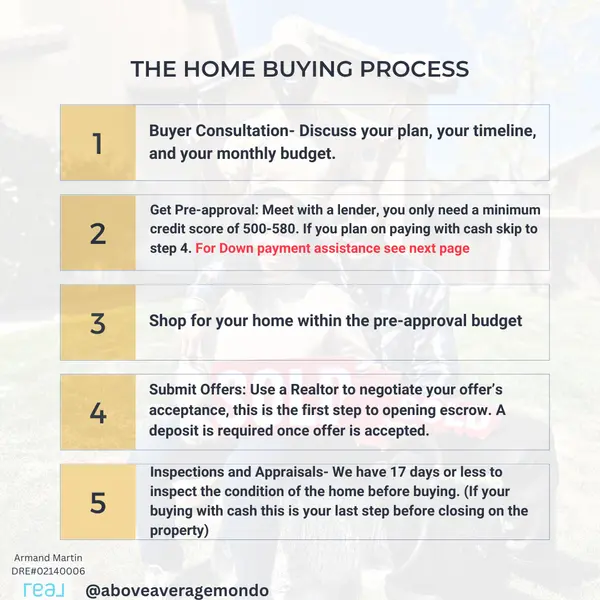
1. What purchase price can I qualify for?
2. What would my monthly payment be?
3. How much money would I normally need to close?
4. Which assistance programs could I qualify for?
5. After assistance and potential seller credits, how much would I actually need out of pocket?
Now we have real numbers.
And real numbers allow us to make a real plan.
❓ California Down Payment Assistance FAQ
Do I need 20% down to buy a home in California?
No. Depending on your mortgage and qualifications, you may be able to purchase with substantially less than 20% down.
Can I buy a house in California with $0 down?
Eligible VA and USDA borrowers may qualify for financing without a required down payment. Other buyers may be able to reduce upfront expenses with assistance programs. Closing costs and other expenses still need to be considered.
Is down payment assistance free money?
Not always. Some assistance may be a grant or gift. Other programs use second mortgages, deferred loans, forgivable loans or shared-appreciation loans.
Are there home buyer programs for nurses in California?
Yes, there are programs where eligible healthcare professionals may receive additional benefits. GSFA Platinum is one program worth researching. Nurses can also potentially qualify for programs that aren't occupation-specific.
Can self-employed people qualify for a mortgage?
Yes. Self-employed borrowers can qualify, although lenders may calculate and document their income differently than W-2 employees.
Do I have to be a first-time homebuyer?
Not for every program. Some programs require first-time buyer status while others do not.
What credit score do I need for down payment assistance?
There is no single score for every program. Requirements vary by lender, mortgage and assistance program.
Can down payment assistance work with FHA?
Many assistance programs can work with FHA financing, subject to lender and program requirements.
Can I use assistance with a conventional loan?
Yes. Certain assistance programs can be combined with qualifying conventional financing.
🔑 Ready to Find Out What You Qualify For?
If you've been sitting on the sidelines because you think you need a massive down payment, don't disqualify yourself before you know your numbers.
Whether you're:
👩⚕️ A nurse or healthcare worker
💼 Self-employed
🏠 A first-time homebuyer
🔄 A repeat buyer
🇺🇸 A veteran
👨👩👧👦 A family looking for more space
or simply someone who's tired of renting...
Let's find out what's actually possible.
I'm Armand Martin, a California Realtor and real estate investor, and I help buyers understand the home-buying process in plain English—from getting qualified and finding the right property all the way to getting the keys.
Your first step doesn't have to be buying a house.
Your first step is finding out what's possible.
Visit Martin Investing:
https://martininvesting.com
Ready to get started? Let's find out which California home buyer and down payment assistance programs you may qualify for.
Recent Posts
GET MORE INFORMATION